Imagine waking up in a different time zone to find that 25% of your gross rental income has vanished before it even reached your bank account. For many expats, the complexities of non-resident landlord tax Canada feel like a constant weight, especially when you’re trying to manage an Ottawa home from thousands of miles away. It’s completely natural to feel overwhelmed by the fear of CRA penalties or the confusion surrounding NR6 and NR4 forms. You’ve worked hard for your investment, and seeing it eroded by administrative hurdles is a stress no homeowner should have to carry.
We believe your time abroad should be spent focusing on your new chapter, not worrying about tax deadlines. This guide provides a clear path to reclaiming control over your finances. You’ll discover how to move from paying tax on gross rent to paying only on your net profit, effectively reducing your monthly burden. We will walk through the steps to establish a reliable compliance system that protects your Ottawa rental investment and offers the peace of mind that comes with professional, steady stewardship.
Key Takeaways
- Understand why the CRA mandates a 25% withholding on gross rent and how you can transition to a more favorable tax structure.
- Learn how to leverage a Section 216 election to pay non-resident landlord tax Canada on your actual net profit, allowing for key expense deductions.
- Explore the benefits of the NR6 form, which can lower your monthly withholding tax and keep more cash in your pocket throughout the year.
- Master the essential CRA calendar, from monthly remittances to annual NR4 slips, to protect yourself from costly non-compliance penalties.
- Discover how partnering with a Canadian agent provides the professional oversight needed to manage your Ottawa property with total confidence.
The 25% Rule: Understanding Non-Resident Withholding Tax in Canada
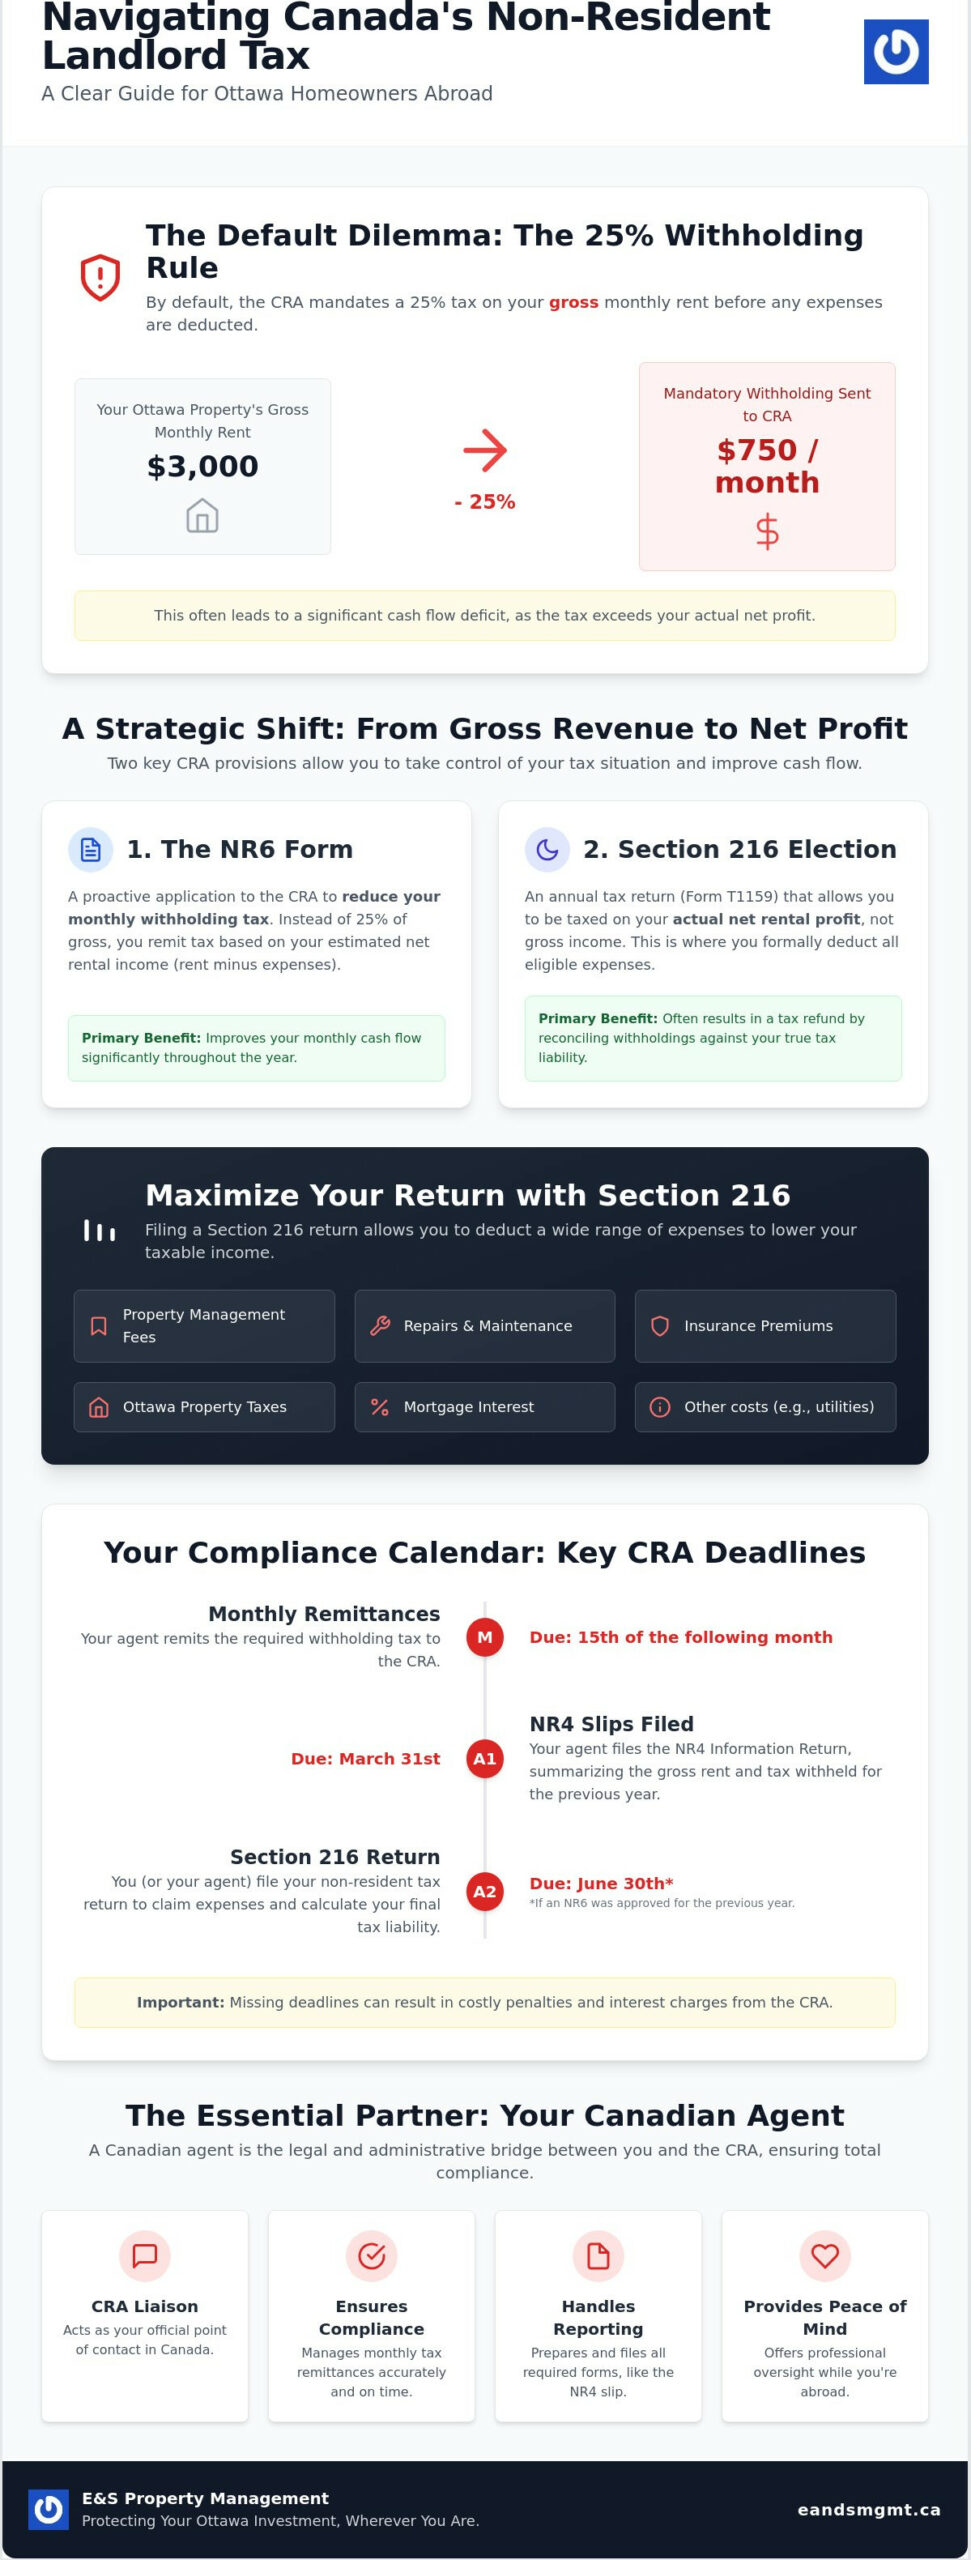
The default requirement for non-resident landlord tax Canada is often the first hurdle that catches owners by surprise. Under Part XIII of the Income Tax Act, the Canada Revenue Agency (CRA) mandates a 25% withholding tax on the gross rental income of non-residents. This isn’t necessarily your final tax bill; it’s a security measure to ensure Taxation in Canada remains consistent even when the property owner lives abroad. The challenge lies in the definition of “gross rent.” This term refers to the total amount your tenant pays before you deduct a single cent for your mortgage interest, property taxes, or repairs. If your Ottawa home rents for $3,000, the CRA expects $750 every month, regardless of whether your actual take-home profit is only a few hundred dollars.
Legally, the responsibility for remitting this tax falls on the person or entity paying the rent to you. While recent legislative updates, such as Bill C-15, have clarified that individual residential tenants are no longer required to withhold and remit this tax, the burden hasn’t disappeared. It remains firmly on the non-resident landlord or their designated agent. This shift highlights the need for a reliable partner on the ground who can manage the rhythmic cycle of monthly remittances and ensure you stay in the CRA’s good graces.
Who Qualifies as a Non-Resident Landlord?
Determining your status involves more than just counting days spent outside the country. The CRA looks at your primary residential ties, such as a home, spouse, or dependents remaining in Canada. For members of the Foreign Service or DND on posting, residency status is particularly nuanced. You might be a “deemed resident” or a non-resident depending on the specifics of your assignment and your ties back home. It’s vital to notify the CRA of your change in status to avoid the sudden shock of back-dated penalties or unexpected withholding requirements that can disrupt your financial planning.
The Consequences of the Default 25% Withholding
Accepting the default 25% withholding often leads to a significant monthly cash flow deficit. For many Ottawa owners, the gross tax payment exceeds their actual rental profit, meaning they’re effectively paying out of pocket to keep their investment running. Recovering these overpayments is possible, but it’s a slow and administrative process that can take years without the right elections in place. A Canadian Agent is a resident individual or entity that acts as the legal bridge between a non-resident landlord and the CRA to ensure all withholding and reporting requirements are met. Without this professional oversight, you’re left to manage complex deadlines from a different time zone, risking both your profit and your peace of mind.
Section 216 Election: Paying Tax on Net Income, Not Gross
The 25% flat tax on gross income often feels like an unfair penalty for owning property while living abroad. Fortunately, the Section 216 election serves as a vital tool for those managing non-resident landlord tax Canada. It allows you to shift the CRA’s focus from your total revenue to your actual profit. By electing to file a Section 216 return (Form T1159), you’re taxed at graduated rates on your net income, which is almost always a more sustainable path for Ottawa homeowners. This election transforms your rental from a potential cash drain into a carefully managed asset.
According to the CRA Guide to Section 216 Election, if an NR6 form for the 2025 tax year was approved, the corresponding Section 216 return must be filed on or before June 30, 2026. This process allows you to claim back overpaid tax, potentially resulting in a significant refund. It’s a rhythmic part of the annual cycle that brings order and financial clarity to your investment. Many clients find that professional financial reporting and accounting makes this transition from stress to relief much smoother by ensuring every receipt is captured and categorized correctly.
Eligible Expenses You Can Deduct
When you file under Section 216, you can deduct a wide range of expenses incurred to earn rental income. This includes property management fees, repairs, maintenance, and insurance. Ottawa property taxes, which are a significant fixed cost, are also fully deductible. It’s vital to distinguish between mortgage principal and interest; only the interest portion is a deductible expense. By meticulously tracking these costs, you protect your profit margins and ensure you aren’t paying more tax than legally required.
Gross vs. Net: A Financial Comparison
The difference between the default withholding and the Section 216 election is often dramatic. Below is a typical scenario for an Ottawa rental property to illustrate the potential savings.
| Expense Category | Default 25% Withholding | Section 216 Election (Net) |
|---|---|---|
| Monthly Rent | $3,000 | $3,000 |
| Monthly Tax Payment | $750 | $0 to $225 (Estimated) |
| Deductible Expenses | Not Applicable | $2,100 (Interest, Taxes, Fees) |
| Taxable Income | $3,000 (Gross) | $900 (Net Profit) |
As shown, the Section 216 election can save an owner hundreds of dollars every month. Instead of losing a quarter of your revenue, you’re only paying tax on the money that actually stays in your pocket. This approach significantly improves your long-term ROI and provides the peace of mind that your Ottawa home is working for you, not against you.
The NR6 Form: Reducing Your Monthly Tax Burden
While the default 25% withholding on gross rent provides the CRA with security, it often leaves owners with a significant monthly cash flow deficit. The NR6 form serves as a proactive remedy, allowing you to pay non-resident landlord tax Canada based on your estimated net profit rather than your total revenue. By providing a clear picture of your expected income and expenses before the year begins, you can drastically reduce the amount of tax withheld from each rent payment. This transition from gross to net withholding ensures your Ottawa investment remains a source of steady income rather than a monthly financial strain.
According to the Canada Revenue Agency guidelines on non-resident rental income, this form must be submitted on or before January 1st of each year, or before the first rental payment is due. Missing this precise window means you’re required to continue with the default 25% gross withholding until the following calendar year. It’s a logistical requirement that demands careful planning and an accurate understanding of your property’s financial performance. When you’re living in a different time zone, having a seasoned hand to manage this timeline provides a sense of order and clarity that’s difficult to achieve alone.
Step-by-Step NR6 Filing Process
The journey to reduced withholdings begins with a realistic estimation of your annual rental income and deductible expenses. You’ll need to account for property taxes, insurance, and maintenance costs to arrive at a precise net figure. Once these numbers are finalized, you must secure a Canadian Agent who’s willing to co-sign the NR6 undertaking with you. After the CRA reviews and approves your submission, they’ll issue a letter of authorization. Only then can your agent begin withholding tax at the lower rate, providing you with immediate relief and improved monthly liquidity throughout the year.
The Role of the Canadian Agent in NR6 Compliance
Acting as a Canadian Agent is a significant responsibility that involves more than just signing a document. Under the NR6 agreement, the agent becomes personally liable for any unpaid taxes if the non-resident landlord fails to file their final Section 216 return. While a family member might offer to help, the legal complexities and potential financial risks often make a professional property manager a more reliable choice. E&S Property Management has provided specialized NR6 and NR4 tax filing support since 1981, acting as a protective guardian for Foreign Service members and expats. We understand the administrative rhythm required to keep your Ottawa home protected, ensuring every filing is meticulous and every deadline is met with quiet confidence.
Key CRA Deadlines and the Cost of Non-Compliance
Managing non-resident landlord tax Canada requires a steady, methodical approach to the calendar. The CRA operates on strict timelines; for an expat living in a different time zone, missing a single date can trigger a cascade of administrative stress. Establishing a rhythmic cycle for your filings is the best way to move from anxiety to relief. This professional oversight ensures that your Ottawa investment remains protected and your standing with the CRA remains beyond reproach.
The first date to memorize is the 15th. Any tax withheld from your rental income must be remitted to the CRA by the 15th of the month following the month the rent was paid. If your tenant pays rent in July, the remittance is due by August 15th. Staying on top of this monthly requirement is vital. While the monthly cycle is frequent, the annual requirements are equally critical. If you’ve elected to file under Section 216 and had an NR6 approved, your return is generally due by June 30th. However, if you owe any remaining tax, that balance must be paid by April 30th to avoid interest charges. The CRA’s late-filing policy is famously rigid for non-residents, and extensions are rarely granted.
Understanding NR4 Slips
An NR4 slip is the official statement of the gross rental income paid to you and the total tax withheld during the calendar year. These slips must be issued to both the CRA and the landlord by the last day of February. Common errors, such as using an incorrect non-resident account number or mismatched income totals, are frequent triggers for CRA audits. Professional management ensures these documents are prepared with meticulous care, reflecting an accurate financial narrative of your property’s performance without the risk of administrative oversight.
Penalties: More Than Just a Slap on the Wrist
The financial consequences of missing deadlines can be significant. Late-payment interest is calculated daily, and failure-to-remit penalties can quickly erode your rental profits. Perhaps most importantly, chronic non-compliance can jeopardize your eligibility to use the Section 216 election in the future, potentially forcing you back to the 25% gross withholding model. Compliance is the only insurance against CRA audits. By delegating these responsibilities to a seasoned hand, you ensure every form is filed with precision. If you’re ready to simplify your obligations, our team provides comprehensive NR6 and NR4 tax filing support to keep your investment on track.
Professional Tax Administration: How E&S Protects Your Ottawa Investment
The administrative burden of non-resident landlord tax Canada is significant, but it doesn’t have to be a solo journey. While previous sections of this guide detailed the “what” and “when” of CRA compliance, the “how” involves finding a partner who integrates these tasks into a single, stabilizing force. The synergy between full-service property management and specialized tax administration means every repair receipt is already captured for your Section 216 election, and every monthly rent payment is correctly remitted before the deadline even approaches. This integration ensures that your financial reporting is meticulous and your standing with the CRA is protected, allowing you to move from a cycle of constant worry to a state of quiet confidence.
We act as the essential legal bridge between you and the Canada Revenue Agency. As your Canadian Agent, we take on the formal responsibility of co-signing your NR6 undertaking and managing the monthly withholdings. This role is a legal necessity for non-residents who wish to pay tax on net profit rather than gross revenue. While many firms focus purely on the accounting aspect, E&S Property Management provides end-to-end stewardship. We manage the tenant relations and property inspections while simultaneously ensuring your tax filings are handled with precision. This comprehensive approach simplifies your life, allowing you to focus on your responsibilities abroad while we care for your asset at home.
A Tailored Approach for Foreign Service & DND
Ottawa is a unique hub for global postings, and we’ve been deeply rooted in this community since 1981. We understand the specific administrative rhythm of Global Affairs and DND postings because we’ve been navigating these complexities for over 40 years. Our team recognizes the personal value of your Ottawa home and the anxiety that can come with a change in residency status. We’ve helped hundreds of families move from the stress of tax confusion to the relief of professional oversight, ensuring their homes are ready for their eventual return.
Get Started with E&S Property Management
Transitioning your property to professional management is a straightforward process designed to restore your peace of mind. During our initial consultation, we’ll assess your specific tax administration needs and help you establish a “set and forget” compliance system. From tenant placement to emergency 24/7 maintenance response, every service we offer is designed to protect your investment and simplify your obligations. You deserve to enjoy your time overseas without the burden of complex tax forms or the fear of CRA penalties.
Protect your Ottawa investment and simplify your taxes with E&S Property Management
Secure Your Ottawa Investment for the Future
Managing your property from abroad doesn’t have to be a source of constant administrative anxiety. By utilizing the Section 216 election and the NR6 form, you can effectively shift the focus from gross revenue to actual profit. This strategic choice keeps more cash in your pocket while ensuring your standing with the CRA remains secure. Navigating the rhythmic cycle of non-resident landlord tax Canada requires precision, but you don’t have to carry that burden alone. Professional stewardship is the bridge that turns a complex series of deadlines into a manageable, orderly system.
With over 40 years of expertise, we serve as a trusted partner for Foreign Service and DND members. Our specialized NR6 and NR4 administration services provide the clarity you need to focus on your life overseas while we act as the protective guardian for your asset at home. Let E&S Property Management Handle Your Non-Resident Tax Compliance and experience the relief of knowing your financial obligations are in seasoned hands. Your Ottawa home is a valuable part of your future; with the right oversight, it’ll be ready and waiting for your eventual return.
Frequently Asked Questions
What happens if I forget to file my NR6 form by January 1st?
If you miss the January 1st deadline, you must default to withholding and remitting 25% of the gross rent until the CRA approves a subsequent NR6 submission. Approval isn’t retroactive, so you’ll face a period of higher withholdings that can significantly impact your monthly cash flow. While you can eventually recover these overpayments by filing a Section 216 return at year-end, the immediate loss of liquidity can be a burden for many owners.
Can my tenant act as my Canadian agent for non-resident tax?
While a tenant can technically act as a withholding agent, it’s rarely a practical or secure solution for residential properties. Recent legislative updates through Bill C-15 have removed the requirement for individual tenants to withhold tax, shifting the focus to the landlord or their professional agent. Most tenants aren’t equipped to manage the legal liabilities or the precise monthly remittance cycle required for non-resident landlord tax Canada compliance.
Do I still need to file a Canadian tax return if I have no rental profit?
Yes, you should still file a Section 216 return even if your property shows no rental profit for the year. Filing allows you to report a loss, which can often be carried forward to offset future rental income when your property becomes more profitable. More importantly, if you had an approved NR6 form, filing the return is a mandatory requirement to fulfill your legal undertaking and avoid CRA penalties.
How does the CRA define a “Canadian Agent” for non-resident landlords?
The CRA defines a Canadian Agent as a person or entity resident in Canada who acts on behalf of a non-resident landlord to manage tax obligations. This agent is responsible for withholding the correct amount of tax from rent payments and remitting it to the CRA by the 15th of each month. Crucially, the agent accepts personal liability for any unpaid tax if the landlord fails to fulfill their final filing duties.
Can I deduct property management fees on my Section 216 return?
You can absolutely deduct property management fees on your Section 216 return as a legitimate business expense. These fees are considered a direct cost of earning rental income, along with repairs, insurance, and Ottawa property taxes. Deducting these professional fees is a key strategy for reducing your taxable income, ensuring you only pay tax on your actual net profit rather than your gross revenue.
What is the difference between an NR4 and an NR6?
The NR6 is a proactive form filed at the start of the year to request lower monthly withholding based on your estimated net income. In contrast, the NR4 is a reactive slip issued by the end of February that reports the actual gross income and total tax withheld during the previous calendar year. You can think of the NR6 as your financial plan and the NR4 as your year-end summary for the CRA.
Is there a penalty for late-filing a Section 216 return?
There are significant penalties for late-filing, especially if you benefited from reduced withholdings via an NR6 form. If the return isn’t filed by the June 30th deadline, the CRA may void your election and demand the full 25% tax on gross income plus interest. Additionally, any tax balance owing must be paid by April 30th to avoid daily interest charges that can quickly erode your rental profits.
How do I stop non-resident withholding tax if I move back to Ottawa?
To stop non-resident withholding tax, you must officially notify the CRA of your return to Canada and your change in tax residency status. It’s also vital to inform your Canadian agent or property manager so they can stop remitting non-resident landlord tax Canada on your behalf. Keeping clear records of your move-in date and your re-established residency ties will ensure a smooth transition back to being a resident taxpayer.