The NR6 form is a cash-flow tool, not just a tax document, and its success depends entirely on having a professional Canadian agent. For many investors living abroad, the standard 25 percent gross withholding requirement often turns a profitable Canadian property into a monthly cash flow burden. It’s a common frustration to see a quarter of your revenue disappear before expenses like property taxes or maintenance are even considered. If you’re seeking NR6 tax form help for non-resident landlords, you likely already know that administrative errors can lead to costly CRA penalties and unwanted audits.
We understand that the complexities of Canadian tax compliance can feel overwhelming from a distance. This guide will help you master the NR6 filing process to reduce your withholding tax and protect your rental cash flow. Compliance is the key to profitability. You’ll learn how to meet the January 1, 2026, deadline for the upcoming tax year and how to properly appoint a Canadian agent to manage your remittances. We also provide a clear timeline for your Section 216 return, due by June 30, 2027, to ensure your investment remains both compliant and profitable.
Key Takeaways
- Learn how the NR6 form allows you to pay tax on net rental profit rather than the 25% gross rent default, protecting your investment’s monthly liquidity.
- Understand the essential role of a Canadian agent in securing CRA approval and managing the ongoing monthly remittance process on your behalf.
- Access professional NR6 tax form help for non-resident landlords to navigate the transition between standard withholding requirements and the annual Section 216 election.
- Establish a clear compliance timeline to meet the January 1st filing deadline and avoid the costly revocation of your net-tax status.
- Discover how integrating tax support with full-service property management removes the administrative burden of cross-border asset oversight.
Understanding the NR6 Form: A Lifeline for Non-Resident Landlords
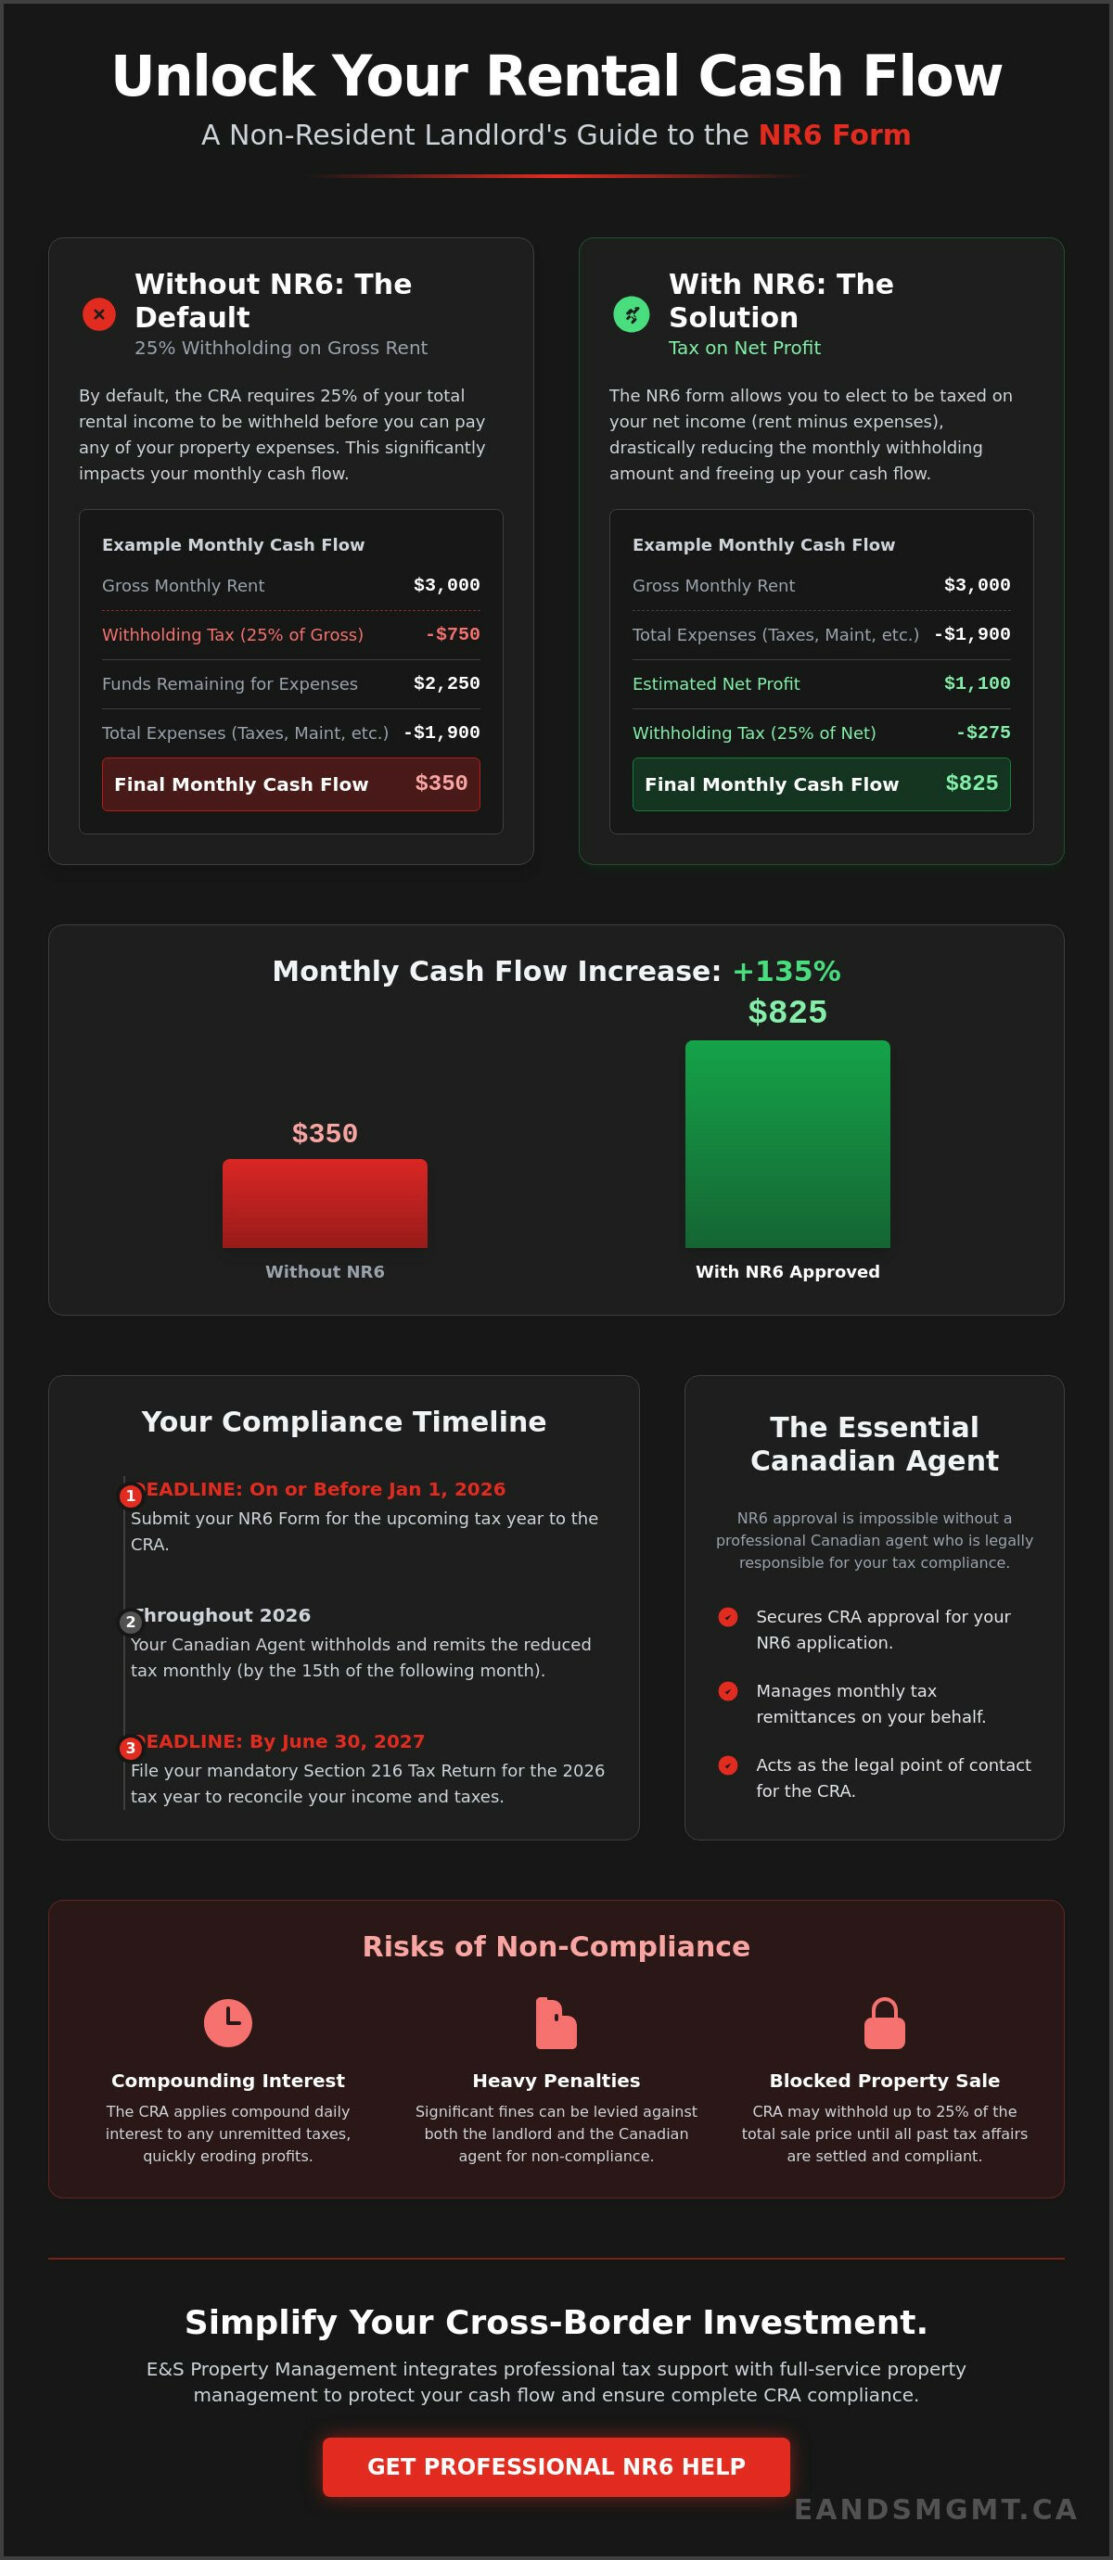
The Canada Revenue Agency (CRA) views rental income earned by individuals living outside the country as a taxable event within Canadian borders. By default, the CRA requires a 25 percent withholding tax on the gross rental income. This means if your property earns $3,000 per month, $750 must be sent to the government before you pay for insurance, property taxes, or emergency repairs. For many investors, this creates a significant cash flow deficit that makes maintaining the asset difficult. Seeking NR6 tax form help for non-resident landlords is the first step toward reclaiming your monthly revenue.
The NR6 form acts as a formal undertaking. It allows you to “elect” to be taxed on your net income rather than the gross amount. Once the CRA approves this form, your withholding is calculated based on the rent remaining after eligible expenses are deducted. This shift often reduces the monthly tax burden from hundreds of dollars to a fraction of that amount. However, this process requires the appointment of a Canadian agent. This individual or firm is legally responsible for withholding the tax and remitting it to the CRA by the 15th of each month. Without a reliable agent, the CRA won’t approve the NR6, and you’ll remain stuck with the 25 percent gross withholding rule.
Who Qualifies as a Non-Resident Landlord?
Residency for tax purposes isn’t just about where you sleep; it’s about your primary residential and social ties. Expats, members of the Foreign Service, and foreign nationals who own Canadian real estate are generally considered non-residents. A common misconception is that simply “leaving Canada” for a few years automatically changes your status. The CRA looks at whether you’ve maintained a home, a spouse, or dependents within the country. Regardless of your specific status, your Ottawa property remains a Canadian tax obligation. Understanding Taxation in Canada for non-residents ensures you don’t inadvertently run afoul of these strict definitions.
The Consequences of Ignoring NR6 Compliance
Ignoring these requirements leads to severe financial repercussions that can compound quickly. The CRA applies compound daily interest to any unremitted taxes, which can erase your profit margins within months. Both the landlord and the Canadian agent can face heavy penalties for failing to withhold or remit correctly. Perhaps the most significant risk occurs during the eventual sale of the asset. Without a documented history of compliance, obtaining a Certificate of Compliance becomes a nightmare. The CRA may withhold up to 25 percent of the total sale price until all past tax affairs are audited and settled. Proactive management prevents these operational burdens from devaluing your investment.
The Section 216 Election: How NR6 Changes Your Tax Withholding
Section 216 of the Income Tax Act provides the legal framework that makes the NR6 form so valuable for property owners. While the default law mandates a flat tax on every dollar collected, Section 216 allows you to treat your rental activity as a business. By electing to file under this section, you’re permitted to pay tax only on your actual profit. This is where professional NR6 tax form help for non-resident landlords becomes essential. The NR6 form itself is technically an “undertaking.” When you sign it, you’re making a binding promise to the CRA that you will file a Section 216 tax return by the June 30th deadline of the following year.
Timing is everything with this election. You must submit the NR6 on or before January 1 of the tax year, or before the first rent payment is received. If you miss this window, the CRA typically requires the full 25 percent gross withholding until the form is processed and approved. For those seeking NR6 tax form help for non-resident landlords, obtaining NR6 and NR4 tax filing support ensures these critical windows aren’t missed.
Gross Withholding vs. Net Withholding
The difference between gross and net withholding is the difference between a struggling investment and a thriving one. Under the standard rules, the CRA ignores your expenses. If you pay $1,500 in mortgage interest and $300 in property taxes on a $3,000 rent, the 25 percent gross tax ($750) is calculated as if those costs don’t exist. By utilizing the CRA guidelines on non-resident rental income, you can deduct eligible expenses like repairs, management fees, and insurance first. This ensures your withholding tax is based on the remaining net income, which keeps more cash in your pocket for mortgage principal payments and capital improvements.
The Agent Requirement Explained
The CRA requires a Canadian resident to act as your agent because they need a local point of contact who is legally responsible for the tax. This agent is not just a mail-forwarder; they are personally liable for withholding and remitting the correct amount by the 15th of every month. Many landlords consider asking a family member to help, but this is a high-stakes role. If a relative misses a filing or miscalculates a remittance, they become legally responsible for the debt. Professional oversight provides a layer of security, ensuring that all technical requirements are met without putting personal relationships at risk.
Calculating the Benefit: Cash Flow Comparison for 2026
Understanding the financial impact of the NR6 election requires a look at the monthly balance sheet. Consider a typical rental property in Ottawa generating $3,000 in monthly rent. Under Scenario A, without an approved NR6, the CRA mandates a 25 percent gross withholding. This results in $750 being sent to the government every month, leaving you with only $2,250 to cover your mortgage, property taxes, and insurance. If your carrying costs exceed this amount, you’re forced to subsidize the property from your foreign income, creating a negative cash flow situation that is difficult to sustain long term.
Scenario B utilizes NR6 tax form help for non-resident landlords to shift the calculation to net income. By filing the Official NR6 Form, you can estimate your eligible expenses for the 2026 tax year. If your monthly expenses including mortgage interest, property taxes, and management fees total $2,000, your net income is only $1,000. The 25 percent withholding is then applied to this net amount, resulting in a $250 monthly remittance. This $500 monthly difference significantly improves your ability to service a Canadian mortgage and maintain a healthy reserve fund while living abroad.
Deductible Expenses for Non-Residents
Maximizing your cash flow depends on accurately identifying all deductible expenses allowed under Section 216. These deductions directly reduce the amount of tax your agent must withhold each month. Common eligible costs include:
- Professional Fees: This includes full-service property management fees and accounting costs related to your rental activity.
- Operational Costs: Property taxes, landlord insurance premiums, and utility costs not paid by the tenant.
- Maintenance: Repairs, landscaping, snow removal, and professional cleaning services required to maintain the asset.
- Financing: The interest portion of your mortgage payment is deductible, though the principal portion is not.
The NR4 Slip: Closing the Loop at Year-End
The NR4 slip is the formal document that summarizes your total gross rental income and the total tax withheld throughout the calendar year. Your Canadian agent is responsible for issuing this slip to both you and the CRA by the March 31st deadline of the following year. This document is critical because it serves as the official record used to reconcile your accounts when you file your Section 216 tax return. If there’s a discrepancy between your NR4 and your actual expenses, it can trigger a CRA review. Ensuring your agent provides accurate financial reporting and accounting throughout the year prevents these administrative hurdles during the final filing stage.
Step-by-Step Guide to Filing Your NR6 Form for 2026
Executing a successful NR6 election requires precision and adherence to a strict chronological order. The process begins with downloading the current version of Form NR6 directly from the CRA website to ensure you’re using the most recent regulatory layout. Once you have the document, you must estimate your 2026 rental income and expenses with high accuracy. These figures aren’t just placeholders; they form the basis of your monthly tax obligations for the entire year. If you need NR6 tax form help for non-resident landlords, our team can provide the NR6 and NR4 tax filing support necessary to ensure your estimates stand up to CRA scrutiny.
After completing the financial projections, your Canadian agent must sign the “Undertaking” section. This signature confirms their legal commitment to withhold and remit the tax on your behalf. You should mail or submit the form electronically well before the January 1, 2026, deadline. It’s vital to remember that you cannot reduce your tax withholding based on your own calculations alone. You must wait for the formal CRA approval letter. Until that document is in your hands, the law requires you to continue withholding the standard 25 percent of gross rent.
The 2026 Compliance Calendar
Maintaining your status as a compliant non-resident landlord requires following a specific annual rhythm. Missing a single date can result in the CRA revoking your NR6 approval and demanding back taxes on gross income. Mark these dates for the upcoming cycle:
- January 1, 2026: Deadline to have your NR6 form approved or at least submitted for the new tax year.
- 15th of Each Month: Your agent must remit the calculated net tax to the CRA for the previous month’s rent.
- March 31, 2027: Deadline for your agent to file the NR4 return and provide you with your tax slip.
- June 30, 2027: Final deadline to file your Section 216 income tax return for the 2026 year.
Common Pitfalls to Avoid
The most frequent error is filing the NR6 form late. If the CRA receives your form after you’ve already collected the first month’s rent for 2026, they will likely reject the application for that entire year. Another risk involves failing to open a Non-Resident (NR) tax account before submission. Without this account number, the CRA cannot process your remittances, leading to administrative chaos and potential interest charges. Finally, be cautious with your expense estimates. While it’s tempting to maximize deductions to lower withholding, gross underestimation of income can trigger a full audit of your Section 216 return. Accuracy is your best defense against CRA intervention.
How E&S Property Management Simplifies CRA Compliance for Expats
Managing a cross-border investment requires more than just a tax filing; it requires a local partner who understands the operational and regulatory details. E&S Property Management provides comprehensive NR6 tax form help for non-resident landlords by acting as your designated Canadian agent. Unlike accounting firms that only handle paperwork, we manage the entire lifecycle of your rental income. We don’t just sign the form. We provide the administrative infrastructure to ensure your property remains a performing asset while you’re abroad.
Our team automates the monthly tax withholding and remittance process. Every month, we calculate the net tax based on your actual property expenses and remit the funds to the CRA by the 15th. This systematic approach removes the risk of late-payment interest or the revocation of your NR6 status. When the tax year concludes, we manage the issuance of your NR4 slips. This ensures you have the accurate financial reporting and accounting data necessary to meet the June 30th Section 216 filing deadline without stress. For Ottawa-based Foreign Service and DND members, our localized expertise ensures your specific posting requirements are reflected in your property’s management plan.
Comprehensive Oversight for Absentee Landlords
Effective non-resident management extends beyond tax compliance. It involves protecting the physical and financial integrity of your Ottawa asset. Our full-service property management includes professional tenant placement services to find reliable occupants who respect your home. We perform regular property inspections to identify maintenance needs before they become costly repairs. You receive transparent financial reporting accessible from anywhere in the world, giving you a clear view of your property’s performance. By coordinating emergency 24/7 maintenance responses, we ensure your tenants are supported and your investment is preserved, regardless of your time zone.
Peace of Mind for Your Posting Abroad
The administrative burden of being a non-resident landlord can be overwhelming, especially when navigating the complexities of the Income Tax Act from another country. We’ve spent over 40 years refining our processes to meet the exact standards required by the CRA. Our role is to serve as the steady hand that manages the chaos of cross-border oversight. We provide a tailored resolution to every challenge, from tax remittances to emergency plumbing repairs. This disciplined approach allows you to focus on your career or posting abroad with the confidence that your Canadian assets are being managed by seasoned professionals. Contact E&S Property Management for NR6 assistance to secure your rental cash flow today.
Protecting Your Assets with Proactive Tax Compliance
Mastering the NR6 filing process is the most effective way to transition from a 25 percent gross withholding burden to a sustainable, profit-based tax model. By appointing a professional agent and adhering to the strict January 1st deadline, you ensure your Canadian rental property remains a predictable source of income. We’ve explored how accurate expense estimation and timely Section 216 filings protect your liquidity and prevent costly CRA intervention. If you’re looking for NR6 tax form help for non-resident landlords, partnering with a seasoned expert removes the operational friction of international ownership.
E&S Property Management brings over 40 years of specialized expertise to every asset we oversee. Our team provides dedicated NR6 and NR4 administration tailored specifically for Foreign Service and DND members stationed abroad. With an A+ rating for reliability and asset protection, we serve as the steady hand you need to navigate complex CRA requirements. Let us manage the administrative details so you can focus on your posting with total confidence. Secure Your Ottawa Property & Simplify Your Taxes with E&S today. Your investment deserves the security of professional stewardship.
Frequently Asked Questions
When is the deadline to file the NR6 form for 2026?
The Form NR6 must be submitted on or before January 1, 2026, or before the first rental payment is received for the new year. Filing early ensures the CRA has sufficient time to process the application so you can begin withholding based on net income immediately in January. If the form is submitted late, the CRA will reject the application for that calendar year.
Can my tenant act as my agent for NR6 purposes?
A tenant can technically act as a Canadian agent, but they must be a resident of Canada and willing to accept the legal liability for withholding and remitting your tax. Most tenants are reluctant to take on this administrative burden and the potential financial penalties associated with non-compliance. Professional property management provides a more stable and reliable resolution for this high-stakes requirement.
What happens if I forget to file my NR6 form?
If you fail to file the NR6 on time, you are legally required to withhold 25 percent of the gross rental income and remit it to the CRA. You cannot retroactively apply for net withholding for months that have already passed. Failure to remit the 25 percent gross amount can lead to daily compound interest and significant penalties for both the landlord and the agent.
Do I still need to file a Canadian tax return if I file an NR6?
Yes, filing an NR6 is an undertaking that specifically obligates you to file a Section 216 income tax return. For the 2026 tax year, individual landlords must submit this return by June 30, 2027. This return is the final step where you reconcile your actual expenses against the estimates provided on your NR6 to determine your final tax obligation.
Can I deduct mortgage payments on my Section 216 return?
You can only deduct the interest portion of your mortgage payments; the principal portion is not an eligible deductible expense. Other common deductions include property taxes, insurance premiums, and professional management fees. Accurate financial reporting and accounting are essential to ensure these deductions are properly documented and stand up to potential CRA scrutiny during an audit.
How do I open a non-resident tax account with the CRA?
You can open a non-resident tax account by contacting the CRA International Tax Services Office or by submitting your first NR6 form for processing. The CRA will assign a specific account number beginning with an “N” to track your monthly remittances. Seeking NR6 tax form help for non-resident landlords ensures this account is established correctly before your first rental payment is due.
Is the NR6 form required every year?
Yes, the NR6 form must be submitted and approved by the CRA every year to maintain your net-withholding status. It’s not an automatic renewal process. If you miss the January 1st deadline for any subsequent year, your agent is legally obligated to revert to withholding 25 percent of the gross rent until a new approval letter is received from the CRA.
What is the difference between an NR6 and an NR4?
The NR6 is an application filed at the start of the year to request withholding on net income, while the NR4 is a summary slip issued after the year ends. The NR4 reports the total gross income and the total tax remitted to the CRA throughout the year. Your agent must file the NR4 by March 31st of the following year to provide the documentation needed for your return.